English
 Arabic
 Français
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
 Réunionnais
 India
Accord énergétique de 540 millions de dollars entre la Chine et les talibans en Afghanistan. Qu'est-ce que cela signifie?
Finance - Investissement |
2023-03-09 14:10:31
 Entreprises locales
 Runsound music
 La silver économie
 Affiliation Matrice 3x9
 Récompenses
 Babarun (BBRN)
 Calculez vos calories
 Collab Influenceurs
 Événementiels
 Procaly
 Affiliation
 Prêts Immobiliers
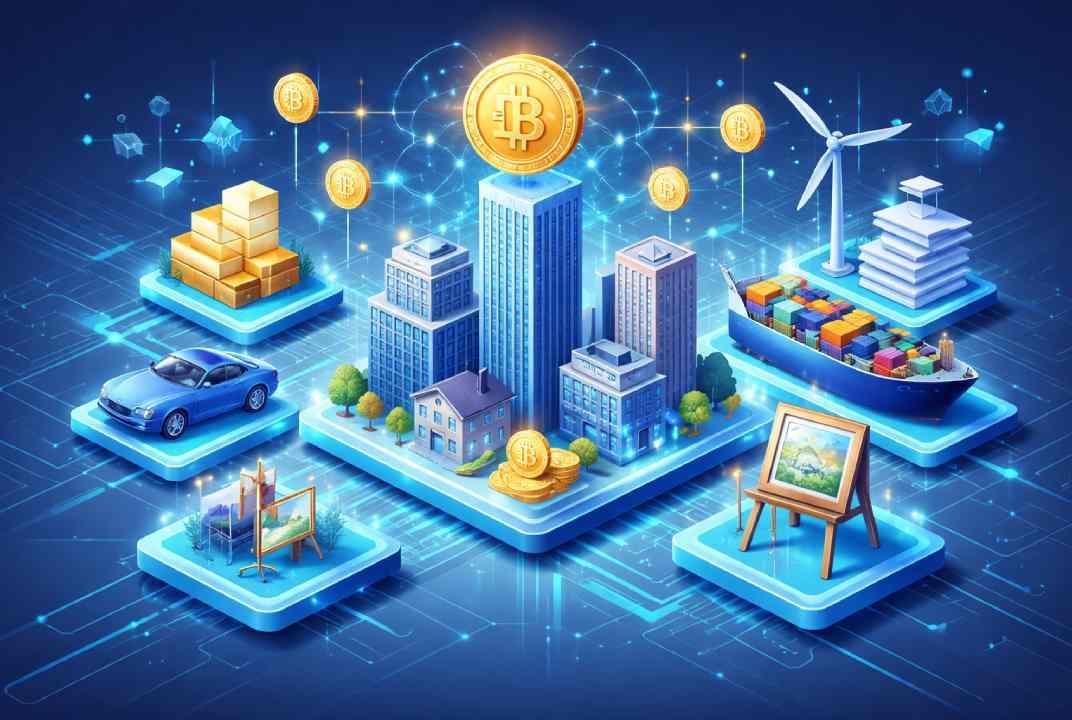
Compliance has traditionally operated around financial assets rather than inside them. An asset may have eligibility requirements, transfer restrictions, ownership limits, reporting obligations, and other regulatory conditions. These rules are often managed through separate legal documents, databases, intermediaries, and compliance workflows. Asset tokenization introduces another possibility: embedding selected compliance requirements into the digital infrastructure that represents an asset.
Instead of treating compliance as a process that happens before or after a transaction, tokenized asset structures can potentially make certain rules part of the transaction itself. This could change how businesses manage ownership, transfers, investor eligibility, and asset lifecycle events.
Asset tokenization is the process of representing ownership, economic interests, or other rights associated with an asset through blockchain-based tokens. A tokenized asset can be designed with programmable conditions.
For example, a token may only be transferable when:
This creates a basic relationship:
Asset → Digital Rights → Compliance Rules → Programmable Transaction
The blockchain does not replace the legal framework. Instead, it can provide technology for enforcing specific rules that are suitable for automation.
In traditional financial infrastructure, compliance can be fragmented across different systems.
Consider a regulated asset transfer:
Investor Request → Identity Check → Eligibility Review → Compliance Approval → Transfer → Record Update
Each stage may involve separate systems or intermediaries. With a suitably designed tokenized structure, some of these checks could occur within the transaction workflow.
For example:
Transfer Request → Wallet Verification → Rule Check → Approved Transfer
The result is a closer relationship between the asset and the conditions governing its movement.
Smart contracts can execute predefined rules automatically. A tokenized security, for example, could be configured so that transfers are permitted only between approved addresses.
This can potentially support rules relating to:
Rather than relying entirely on an external manual approval process, certain objective requirements can become part of the token's transaction logic. However, smart contracts should enforce only rules that are properly defined and technically verifiable.
Know Your Customer processes are fundamental to many regulated financial products. In a tokenized environment, verified investor identity can potentially be connected with wallet permissions.
A simplified process could look like:
Identity Verification → Investor Approval → Wallet Whitelisting → Token Eligibility
Once a wallet is associated with an approved participant, the platform can use that status when processing token transfers. This can help create a system in which ownership is not treated independently from investor eligibility.
Anti-money-laundering requirements can involve transaction monitoring, wallet screening, identity checks, and risk assessment. Tokenization platforms can integrate compliance services that evaluate participants or transactions before transfers are executed.
For example:
Token Transfer Request
↓
Wallet & Participant Screening
↓
Compliance Rules
↓
Approval or Rejection
↓
Settlement
This architecture can make compliance checks part of the digital transaction flow rather than a completely separate administrative activity.
Some financial structures may impose limits on how much of an asset a particular participant can hold. Tokenized infrastructure can potentially track holdings automatically.
For example, a platform could maintain rules such as:
Investor A → Maximum Holding Limit
Investor B → Maximum Holding Limit
Investor Group → Aggregate Ownership Threshold
When a new transaction is initiated, the system can evaluate the current ownership state before allowing the transfer. This can reduce reliance on manually reconciling ownership records.
Traditional assets may have contractual restrictions governing when and how ownership can change. A tokenized asset can potentially represent these restrictions through programmable transfer logic.
For example, tokens could be restricted during:
This creates an important distinction between a basic digital representation and a programmable asset structure. The token does not simply record ownership; it can potentially help enforce conditions surrounding ownership.
Investor eligibility is not necessarily permanent.
An investor's status can change because of:
A tokenization platform can potentially maintain an updatable compliance status associated with an investor or wallet.
This creates a dynamic model:
Approved → Eligible → Transfer Allowed
or
Restricted → Transfer Blocked
The exact implementation depends on the regulatory and technical architecture.
Real estate is another area where tokenized structures may benefit from integrated compliance. A tokenized property investment could involve requirements around investor eligibility, ownership structure, transfer restrictions, and distributions.
A platform could connect:
Property Structure → Investor Verification → Token Ownership → Transfer Rules → Distribution
For example, only verified investors could receive tokens representing an interest in a property-owning entity. The platform could also apply predefined transfer conditions when ownership changes. This can make compliance part of the infrastructure supporting the property investment structure.
Bond Tokenization provides another example.
A tokenized bond can have predefined characteristics such as:
Some of these conditions can potentially be represented within smart-contract logic. When a transaction occurs, the platform can evaluate whether the relevant conditions are satisfied. This could create a more integrated relationship between the bond's financial characteristics and its compliance requirements.
Assets can experience events such as:
Determining which investors are eligible for these events can sometimes require significant administrative coordination. Tokenized infrastructure can potentially use ownership records and predefined eligibility rules to identify relevant participants.
For example:
Record Date → Eligible Token Holders → Rule Validation → Distribution
This can make certain asset lifecycle processes more programmable.
A major opportunity is to integrate compliance across the entire asset lifecycle.
Legal and regulatory requirements are established.
Participants undergo identity and eligibility checks.
Tokens are issued according to the approved structure.
Approved participants hold the relevant tokens.
Transaction rules are evaluated before ownership changes.
Eligible holders receive payments according to predefined conditions.
Tokens are redeemed when the relevant conditions are satisfied. This creates a lifecycle in which compliance is present throughout the asset's journey rather than concentrated at a single point.
| Traditional Model | Tokenized Model |
|---|---|
| Compliance handled through separate systems | Compliance can connect with token infrastructure |
| Ownership records may require reconciliation | Blockchain can provide a shared transaction record |
| Transfer checks may involve manual workflows | Certain checks can be automated |
| Restrictions documented externally | Selected restrictions can be encoded into token logic |
| Eligibility may be checked separately | Eligibility can potentially influence transfer permissions |
| Asset lifecycle processes can be fragmented | Selected processes can become programmable |
Tokenization does not eliminate traditional compliance. Instead, it can potentially add an automated enforcement layer.
Not every regulatory requirement can be converted into a smart contract.
Some compliance decisions require:
This means compliance-native tokenization should not be viewed as “putting all regulations on-chain.”
A more realistic approach is:
Legal Rules + Compliance Systems + External Data + Smart Contracts + Human Oversight
Smart contracts can automate clearly defined conditions, while complex decisions can remain within conventional compliance processes.
Many compliance rules depend on information outside the blockchain.
For example:
Blockchain systems may require trusted external data providers or compliance integrations to access this information. This makes data infrastructure an important part of tokenized compliance. If the underlying data is incorrect, automated rules may produce an incorrect result.
A sophisticated RWA tokenization platform needs to go beyond token creation.
A complete platform may integrate:
The objective is to create an infrastructure layer where asset rights and regulatory requirements can work together.
As tokenization develops, compliance infrastructure could become one of the differentiating components between platforms. A platform that simply creates tokens provides a technical representation of an asset. A more advanced platform can potentially provide:
Token Creation + Identity + Compliance + Ownership + Transfer + Settlement + Reporting
This creates a broader digital asset lifecycle.
For businesses working with regulated or institutionally relevant assets, the ability to manage these components through an integrated platform can be an important part of the tokenization architecture.
Compliance-focused tokenization still faces several challenges.
Rules governing tokenized assets vary across jurisdictions and asset types.
The legal connection between a token and the underlying asset must be clearly defined.
Sensitive identity and compliance information should not simply be exposed on a public blockchain.
Compliance credentials and token permissions may need to work across different platforms and networks.
External data must be reliable because automated systems depend on it.
Errors in programmable compliance logic can create significant operational consequences.
Someone must remain responsible for updating rules when laws, regulations, or asset conditions change.
The broader direction could be toward compliance-aware digital assets. Instead of viewing compliance as an external process surrounding an asset, selected rules could become part of the infrastructure through which that asset operates.
A future tokenized asset might effectively carry a digital rulebook governing:
Who Can Hold It
Who Can Receive It
When It Can Move
How It Can Be Transferred
Who Receives Distributions
When It Can Be Redeemed
This could create financial assets that are not only digitally represented but also capable of interacting with predefined regulatory and operational conditions.
Asset tokenization could change compliance by bringing selected rules closer to the asset's digital structure. Through smart contracts, identity systems, compliance integrations, and programmable transfer controls, certain requirements can potentially become part of the transaction architecture itself. The key shift is from compliance around the asset toward compliance-aware asset infrastructure.
However, tokenization cannot replace legal frameworks, regulators, compliance professionals, or institutional oversight. Its value lies in automating clearly defined processes while keeping complex decisions within appropriate legal and operational structures. As RWA markets develop, this combination of asset rights, programmable rules, verified identity, and transaction infrastructure could become an important foundation for regulated digital assets.